 Facebook
 X
 Pinterest
 Copy Link
The First-Time Home Buyer’s Complete Guide
Two things stop most first time home buyer prospects before they ever make a single phone call. The first is not knowing where to begin. The second is the quiet assumption that they won’t qualify, whether because of credit, income, or not having enough saved. Both of those fears are understandable, and both are usually wrong.
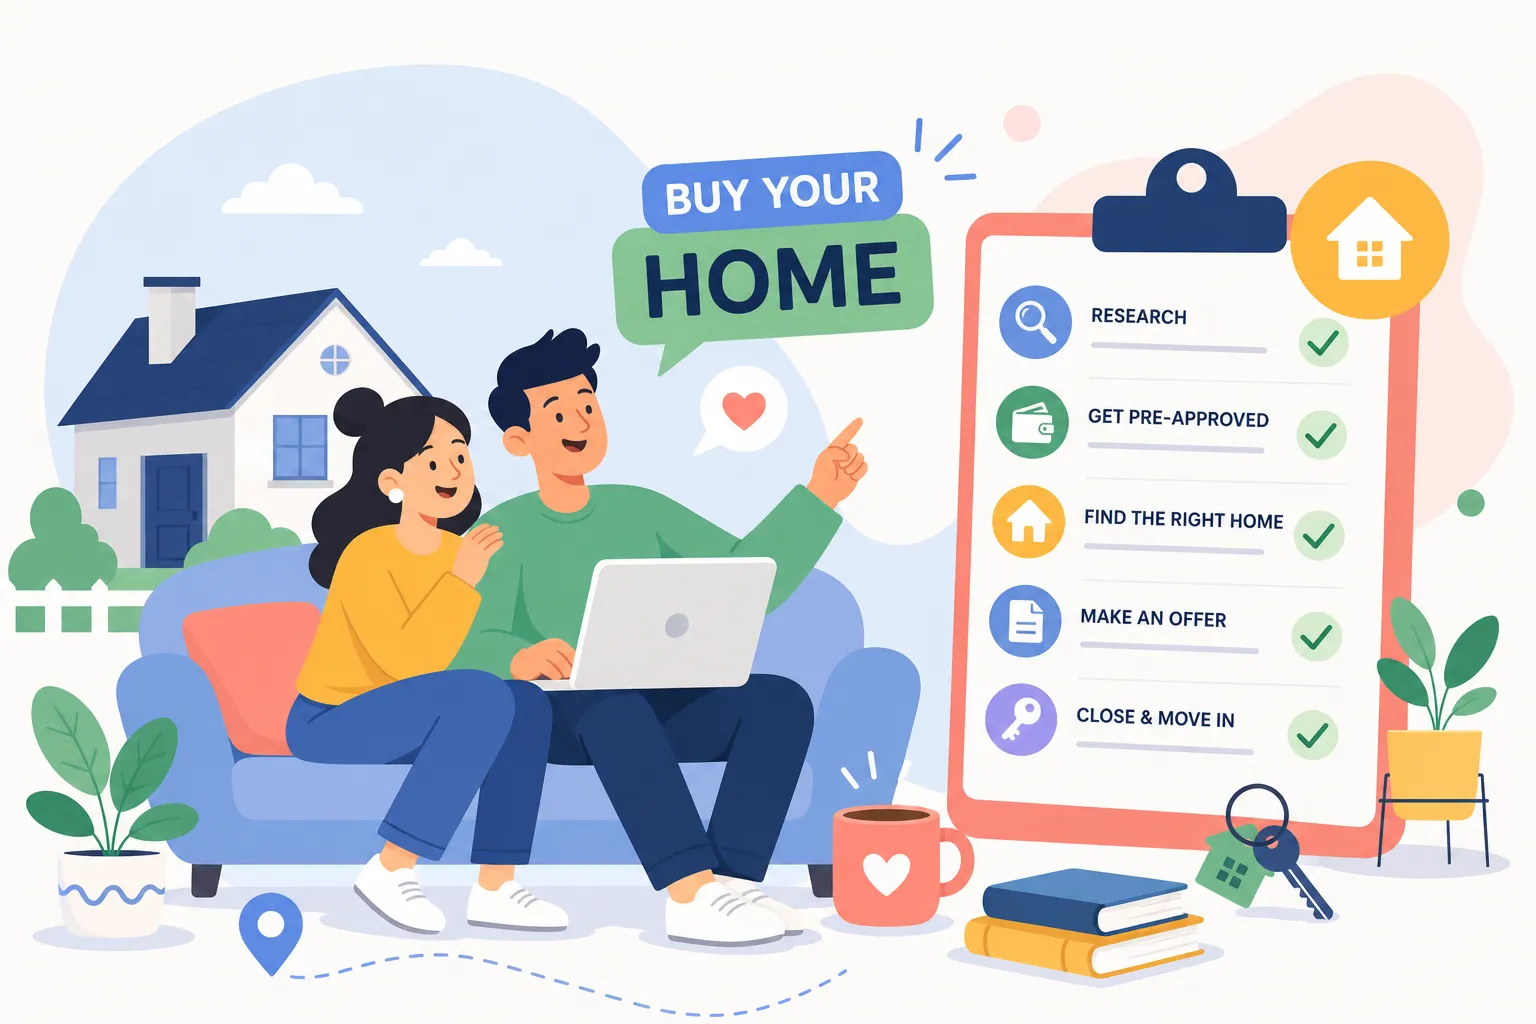
The home buying process has a clear sequence. Once you understand that sequence, it stops feeling overwhelming and starts feeling manageable. There are real loan programs designed for buyers exactly like you, real assistance dollars available in Georgia, and a straightforward path from “I think I want to buy” to holding the keys. By the end of this guide, you’ll know which loan type fits your situation, what “first-time buyer” actually means under program rules, and exactly what steps to take from your first financial check-in to closing day.
Mike Kondalski at ERA Foster & Bond works with buyers at every stage of this process across the Atlanta metro area. His website includes a built-in mortgage calculator so you can start answering the affordability question on your own time, before any conversation with a lender or agent. Think of this guide as the foundation, and that calculator as your first real tool.
What “First Time Home Buyer” Actually Means (and Why You Probably Qualify)
Here’s the part most people get wrong: “first-time buyer” does not mean you have never owned a home in your life. Under most federal, state, and local program definitions, you qualify as a first time home buyer if you have not owned a principal residence during the previous three years. That one rule opens the door for a lot of people who assume they’re locked out.
Divorced buyers who haven’t owned since the settlement, people who sold and rented for a few years, and buyers who owned investment property but never a primary home, all of these buyers can qualify. Couples where only one partner previously owned a home may also qualify, depending on the specific program. The definition is broader than most people expect, and it’s worth checking your own timeline before you write yourself off.
Most programs attach two baseline conditions: the home must be your primary residence, and many programs apply income limits tied to area median income. These aren’t barriers so much as filters. In the Atlanta metro area, Georgia Dream income limits for 2026 go up to $137,555 for a one- to two-person household and $158,188 for households of three or more. That covers a wide range of buyers.
First Time Home Buyer Loan Options Compared
**FHA loans are the most flexible entry point** for buyers with limited savings or imperfect credit. With a 580 or higher credit score, you can put down as little as 3.5%. Debt-to-income standards are more forgiving than conventional loans, which helps buyers carrying student loans or car payments. The trade-off is mortgage insurance: FHA charges an upfront premium of 1.75% of the loan amount (usually rolled into the loan), plus an annual premium of roughly 0.55%. With less than 10% down, that insurance stays for the life of the loan. FHA is the option that says yes more often, but it costs more over time if you stay in the home long-term.
VA loans and USDA loans offer zero down payment for the right buyers. VA loans serve eligible veterans, active-duty service members, and qualifying surviving spouses, with no down payment, no private mortgage insurance, and flexible credit requirements. USDA loans cover buyers purchasing in eligible rural and some suburban areas, with household income limited to 115% of area median income. Neither of these programs is obscure or difficult to access; if you served or you’re buying in a qualifying area, they deserve serious consideration.
Conventional loans with low down payments are worth understanding too. Fannie Mae’s HomeReady and Freddie Mac’s Home Possible programs allow 3% down for moderate-income buyers. When your credit score is solid (620 or above), conventional financing often beats FHA on long-term cost because private mortgage insurance is cancelable once you reach 20% equity. At a 640 credit score with 3.5% down on a $300,000 home, FHA’s monthly insurance runs about $133, while conventional PMI at the same score can run $240 to $360 per month. FHA wins on the monthly payment, but conventional wins if you hold the home long enough to cancel PMI.
First-Time Homebuyer Programs and Down Payment Assistance in Georgia
First-time homebuyer programs come in three main structures, and understanding the difference matters before you apply. A true grant requires no repayment as long as you meet the program’s conditions. A forgivable second mortgage carries no monthly payment and is canceled after you occupy the home for a required period, typically five to ten years. A deferred loan also has no monthly payment, but the balance comes due when you sell, refinance, or move out. Each type has real value; the right one depends on how long you plan to stay.
**Georgia Dream is the primary statewide program** for buyers in this market. It pairs a 30-year fixed first mortgage with a zero-interest deferred second mortgage for down payment and closing cost assistance. The standard program offers 5% of the purchase price up to $10,000. Qualifying public-safety workers, educators, healthcare workers, and active-duty military can access the PEN option at 6% up to $12,500. Buyers or household members with a disability may qualify for the CHOICE option at the same 6% up to $12,500. Purchase price limits in the Atlanta metro area reach $625,000 for 2026, which covers the majority of transactions in Mike’s market area.
Every assistance program comes with conditions you need to know upfront. Georgia Dream requires a minimum 640 credit score, completion of an approved homebuyer education course (the E-Home America online course through DCA costs $50), a minimum $1,000 personal contribution from the buyer, and no more than $20,000 in liquid assets remaining after closing. The assistance is repaid when you sell, refinance, or stop using the home as your primary residence. These are manageable requirements, not traps, but they do need to be part of your plan from the beginning. [First-time buyer grants](https://www.bestmoney.com/mortgage-loans/articles/first-time-homebuyer-grants) and local municipality programs may layer on top of Georgia Dream in some cases, so ask your lender about stacking options specific to your target city or county.
First Time Home Buyer Eligibility: What Lenders Actually Look At
Each loan type has a different starting point for credit scores and debt-to-income ratios. FHA typically works with 580 and up, with DTI around 43% as a soft target. USDA looks for 640 or higher for streamlined underwriting approval. VA has no official minimum from the VA itself, though lender overlays typically require 580 to 620. Conventional loans generally start at 620, with DTI in the 43% to 45% range. These are starting points, not guarantees; a lender’s automated underwriting system looks at the full picture, including reserves, employment history, and how the numbers interact.
Gathering your documentation early is one of the simplest ways to avoid delays later. Here’s what you’ll need for most loan types:
– Two years of W-2s and tax returns (self-employed buyers typically need two years of full returns)
– Recent pay stubs covering the last 30 to 60 days
– Two months of bank statements, with written explanations for any large deposits
– Government-issued photo ID and Social Security number
– Documentation for any other income used to qualify (child support, Social Security, rental income)
– VA buyers: Certificate of Eligibility or service verification
– USDA buyers: household income documentation for all household members
On the FHA vs. conventional question, the honest answer is: run the numbers for both. FHA wins when your credit is below 680 or your DTI is high; the easier approval path and lower monthly insurance payment make it the practical choice. Conventional wins when your credit is solid and you plan to stay in the home long enough to cancel PMI. The only way to see the actual difference is to request Loan Estimates from a lender for both options and compare the five-year total cost. Mike Kondalski’s mortgage calculator gives you a starting point for estimating monthly payments across different purchase prices and down payment scenarios before you sit down with a lender.
Your Step-by-Step Path from Pre-Approved to Keys in Hand
Step 1: Get Your Financial Picture in Order
Pull your credit reports from all three bureaus and look for errors, high balances, or accounts that could drag your score down. Paying down revolving balances below 30% of their limit can move your score meaningfully in a few months. Keep your employment stable; lenders want a two-year history without large gaps. Save for both the down payment and closing costs, which typically run 2% to 5% of the purchase price on top of your down payment. On a $350,000 home, that’s $7,000 to $17,500 in closing costs alone.
Step 2: Choose a Loan Type and Get Pre-Approved
Pre-approval is not the same as pre-qualification. Pre-qualification is an estimate based on what you tell a lender. Pre-approval involves submitting your actual documentation, getting your credit pulled, and receiving a written commitment that holds real weight with sellers. In a competitive market like Atlanta, a pre-approval letter signals to sellers that your offer is serious. Use the mortgage calculator first to pressure-test different purchase prices, then connect with an approved lender to make the pre-approval official. Expect your lender to explain which mortgage programs for first-time buyers you may be eligible for at this stage.
Step 3: Work with a Local Agent and Make Your Offer
A local agent brings context that no listing platform can replicate. Understanding what a fair offer looks like in a specific neighborhood, how to structure contingencies without losing a competitive edge, and what to watch for in a Georgia-specific contract all come from experience in this market. Mike Kondalski and the ERA Foster & Bond team work with first-time buyers throughout the Atlanta metro area, guiding them through offer strategy, negotiation, and every step of the transaction with personalized support rooted in deep local knowledge.
Step 4: Navigate Inspections, Appraisal, and Closing Day
Once your offer is accepted, the clock starts. A home inspection gives you a detailed look at the property’s condition and can support repair requests or price adjustments before you commit. The appraisal confirms the home’s value for the lender and is especially critical for FHA and USDA loans, which have stricter property condition standards. After that, your lender clears any remaining conditions. Your closing attorney, Georgia law requires a licensed attorney at closing, prepares the documents, and you sign. Plan for 30 to 45 days from a complete loan application, and add a buffer if you’re layering in down payment assistance, which requires coordination between your lender and the program administrator.
Frequently Asked Questions for the First Time Home Buyer
Do I have to be a completely new buyer to qualify for first-time homebuyer programs?
No. Most federal and state programs define “first-time buyer” as anyone who has not owned a principal residence in the past three years. If you sold a home, went through a divorce, or only ever owned investment property, you may still qualify.
How much down payment do I actually need?
It depends on the loan type. FHA requires 3.5% with a 580+ credit score. VA and USDA loans require zero down for eligible buyers. Conventional options like HomeReady and Home Possible start at 3%. Down payment assistance programs in Georgia can cover part or all of your required down payment.
What credit score do I need to buy a home?
FHA loans work with scores as low as 580. Conventional loans generally start at 620. Georgia Dream requires a minimum 640. If your score is below these thresholds, a few months of targeted credit work, paying down balances and disputing errors, can make a meaningful difference.
How long does the home buying process take?
From accepted offer to closing typically runs 30 to 45 days. If you’re using down payment assistance, build in additional time for program coordination. Getting pre-approved before you start your search keeps the timeline from stretching once you find a home you want.
You’re Closer to Ready Than You Think as a First Time Home Buyer
The programs are real, the loan options are accessible, and the process follows a clear sequence. Whether you assumed your credit wasn’t good enough, your savings were too thin, or you’d owned before and were automatically excluded, chances are at least one of those assumptions doesn’t hold up under the actual rules.
Start with the mortgage calculator to get a realistic sense of what a monthly payment looks like at different purchase prices. That one step turns “I wonder if I can afford this” into a real number you can work with. From there, the next move is a conversation with a lender to get pre-approved, followed by a conversation with a local agent who knows this market. Expect your lender to ask about your timeline, your credit, and which first-time homebuyer programs you may qualify for, so the more prepared you are going in, the faster that process moves.
Mike Kondalski at ERA Foster & Bond has guided buyers through every part of this process across the Atlanta metro area, from the first financial question to closing day. If you’re ready to find out where you actually stand, reach out to Mike directly for a no-pressure conversation about what your path to homeownership looks like from here.
